Related Topics:
Comprehensive Analysis Supercapacitors-
Analysis of risk factors in the energy storage industry
When insurers are reviewing a BESS project, their primary concern is thermal runaway. Thermal runaway is an uncontrolled exothermic reaction that raises cell temperature and can propagate between cells, occurring when a cell achieves elevated temperatures. Thermal runaway can occur due to mechanical and. Probable Maximum Loss (PML) is an insurer's risk analysis of a project's 'worst case' loss scenario. For BESS projects, the PML is likely to be a thermal runaway event that causes the total. Insurers will always ask for proof that the manufacturers batteries have undergone successful UL9540a testing - the UL9540a is a test method for. Gases being given off by battery cells are an early indicator that a thermal runaway event is occurring, so early detection of gases is critical before a build-up can become volatile. In. Insurers will review the Battery Management System's ability to identify, control, and eliminate potential risk scenarios. Battery.
[PDF Version]
-
Normal operating temperature of supercapacitors in communication base stations
Electrochemical impedance spectroscopy (EIS) is one of the most important analytical tools for characterization of electrochemical double-layer capacitors (EDLC). As an example, we have characterized.
FAQs about Normal operating temperature of supercapacitors in communication base stations
What is the safe operating temperature of a supercapacitor?
Most supercapacitor manufacturers specify the safe operating temperatures in the range of −40 to 70°C. Chapter 2 presents more treatment of the subject matter on Thermal Considerations for Supercapacitors. They have excellent low temperature performance which can meet the power needs in extreme weather conditions in heavy electrical applications.
What are the thermal considerations for supercapacitors?
The ambient temperatures, where the supercapacitors are deployed, have a major influence particularly at the extremes. Most supercapacitor manufacturers specify the safe operating temperatures in the range of −40 to 70°C. Chapter 2 presents more treatment of the subject matter on Thermal Considerations for Supercapacitors.
What is the low temperature performance of a supercapacitor?
420 –20 °C [52,53]. The low temperature performance has been improved by adding particles to the electrode material. The 423 microscale particles and therefore display better kinetics at low temperatures . 426 their low-temperature performance [55–57]. 430 [58,59]. The nature of the charge storage mechanism in supercapacitors makes them
Which Supercapacitors can be used for a broader application range?
A broader application range would also be possible with low temperature low ESR supercapacitors (e.g. for deep space missions) or with high temperature long-term stable supercapacitors (for memory and clock backup). The TRL of the developed BOSC can be considered to be 6.
Why are supercapacitors used in high temperature applications?
On the extreme high-temperature side, for example, in downhole drilling where temperatures are above 120°C, the supercapacitors' ability to function is limited by their electrolytes. Ionic liquids are used in high temperature applications because of their good thermal stability and low vapor pressure.
How does a supercapacitor perform at different temperatures?
The thermophysical properties of these components dictate the electrochemical performance of a supercapacitor at different temperatures, which is reflected by two crucial metrics-capacitance and ESR—and also others such as aging, self-discharge and leakage.
-
Hydrogen production and energy storage benefit analysis
This paper comprehensively describes the advantages and disadvantages of hydrogen energy in modern power systems, for its production, storage, and applications.
FAQs about Hydrogen production and energy storage benefit analysis
How can a hydrogen industry improve the environment?
By identifying and addressing environmental challenges associated with hydrogen production, storage, and utilization, the industry can strive for continuous improvement, minimizing environmental impacts and ensuring a sustainable energy future.
What is the environmental impact of hydrogen production & storage & transport?
The environmental impact of hydrogen production, storage and transport is evaluated in terms of greenhouse gas and energy footprints, acidification, eutrophication, human toxicity potential, and eco-cost.
What are the economic benefits of a hydrogen-based economy?
Energy transition and economic opportunities: The transition to a hydrogen-based economy presents significant economic opportunities. The establishment of hydrogen production, storage, distribution, and utilization infrastructure creates new industries and job opportunities.
Why is hydrogen storage important?
Hydrogen storage is crucial for advancing hydrogen as a sustainable energy source, with physical-based storage methods playing a key role due to their straightforward handling of hydrogen in gas or liquid forms. Three primary methods stand out, each tailored to different needs and applications.
How sustainable is hydrogen production & storage?
However, the sustainability of hydrogen production, storage and transport are neither unquestionable nor equal. Hydrogen is produced from natural gas, biogas, aluminium, acid gas, biomass, electrolytic water splitting and others; a total of eleven sources were investigated in this work.
What are the advantages and disadvantages of hydrogen based technology?
One such technology is hydrogen-based which utilizes hydrogen to generate energy without emission of greenhouse gases. The advantage of such technology is the fact that the only by-product is water. Efficient storage is crucial for the practical application of hydrogen.
-
Charging station energy storage project analysis
The coupled photovoltaic-energy storage-charging station (PV-ES-CS) is an important approach of promoting the transition from fossil energy consumption to low-carbon energy use. However, the integrated.
FAQs about Charging station energy storage project analysis
What is the power of the charging station?
The total power of the charging station is 354 kW, including 5 fast charging piles with a single charging power of 30 kW and 29 slow charging piles with a single charging power of 7.04 kW. The installed capacity of the PV system is 445 kW, and the capacity of energy storage is 616 kWh.
What is the cost-benefit method for PV charging stations?
Based on the cost-benefit method ( Han et al., 2018), used net present value (NPV) to evaluate the cost and benefit of the PV charging station with the second-use battery energy storage and concluded that using battery energy storage system in PV charging stations will bring higher annual profit margin.
How do you assess the environmental cost of a charging station?
To assess and quantify the environmental cost of a charging station, various factors need to be considered, including the electricity generation emissions, the type of energy source used, and the efficiency of the charging stations.
Why is the integrated photovoltaic-energy storage-charging station underdeveloped?
The coupled photovoltaic-energy storage-charging station (PV-ES-CS) is an important approach of promoting the transition from fossil energy consumption to low-carbon energy use. However, the integrated charging station is underdeveloped. One of the key reasons for this is that there lacks the evaluation of its economic and environmental benefits.
What is the optimization model for energy storage and charging station?
Liu et al. (2017) proposed an optimization model for capacity allocation of the energy storage system with the objective of minimizing the investment and operation cost of energy storage and charging station. Hung et al. (2016) analyzed the capacity allocation of the PV charging station.
What is the capacity optimization model of integrated photovoltaic-energy storage-charging station?
The capacity optimization model of the integrated photovoltaic- energy storage-charging station was built. The case study bases on the data of 21 charging stations in Beijing. The construction of the integrated charging station shows the maximum economic and environment benefit in hospital and minimum in residential.
-
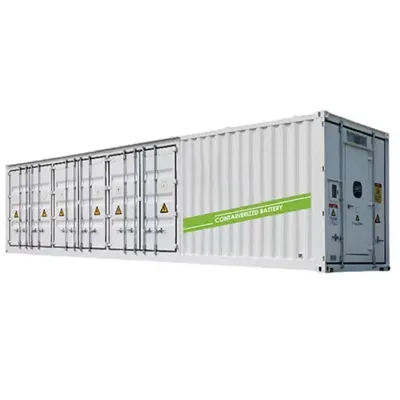
Container Energy Storage Cost Analysis
Using UK market data as a representative case study, Wenergy Technologies compares 3. 016MWh energy storage containers to reveal universal cost principles applicable across global markets.
-
Analysis of electricity cost of communication base stations
The analysis results show that the participation of idle energy storage of 5G base stations in the unified optimized dispatch of the distribution network can reduce the electricity cost of 5G base stations, alleviate the pressure on the power supply of the distribution network, increase the rate of new energy consumption in the system, and realize a win-win situation between the communication operator and the grid.
-

European Battery Enterprise Demand Analysis Report
This report is an output of the Clean Energy Technology Observatory (CETO), and provides an evidence-based analysis of the overall battery landscape to support the EU policy making process.
FAQs about European Battery Enterprise Demand Analysis Report
What are the key factors influencing the European battery market?
The Europe battery market is poised for significant growth, driven by substantial investments in battery technologies and the increasing demand for electric vehicles (EVs) and industrial electrification. The market is segmented by type, technology, and application, with notable advancements in lithium-ion and lead-acid batteries.
How is the European battery market segmented?
European battery market is segmented by type, technology, application, and geography. By type, the market is segmented into primary batteries and secondary batteries. By technology, the market is segmented into lead-acid batteries, lithium-ion batteries, and other technologies.
What are the key trends in battery applications market?
The analysis shows fast growth of battery applications market, especially for EVs, a growing EU share in global production, a technology shift towards larger cells, module-less designs, Chinese Na-ion chemistry and expected growth of less expensive chemistries in the coming years.
Will EU demand for electric vehicle batteries be met by 2025?
87 The production capacity of the EU-based battery industry, although still limited, is developing rapidly and could satisfy expected EU demand for electric vehicle batteries by 2025.
What is the growth rate of Europe battery market?
The Europe Battery Market is growing at a CAGR of 13.44% over the next 5 years. Saft Groupe SA, FIAMM SpA, BYD Co Ltd, Contemporary Amperex Technology Co. Ltd, Tesla Inc. are the major companies operating in Europe Battery Market.
Does the EU monitor battery production?
33 Crucially, the Commission does not monitor EU production of battery cells sufficiently. Eurostat currently reports on quantities (units) of batteries produced44 regardless of their energy capacity in Watt-hours, which is the essential market indicator.
-
Sodium battery price trend analysis chart
The increase in battery demand drives the demand for critical materials. In 2022, lithium demand exceeded supply (as in 2021) despite the 180% increase in production since 2017. In 2022, about 60% of lithium, 30% of cobalt and 10% of nickel demand was for EV batteries. Just five years earlier, in 2017, these shares were. In 2022, lithium nickel manganese cobalt oxide (NMC) remained the dominant battery chemistry with a market share of 60%, followed by lithium iron phosphate (LFP) with a share of just under 30%, and nickel cobalt aluminium. With regards to anodes, a number of chemistry changes have the potential to improve energy density (watt-hour per kilogram, or Wh/kg). For example, silicon can be used to replace all or some of the graphite in the anode in.
FAQs about Sodium battery price trend analysis chart
What is the global sodium-ion battery market size?
The global sodium-ion battery market size was estimated at USD 321.75 million in 2023 and is expected to grow at a CAGR of 16.3% from 2024 to 2030. The global market is experiencing significant growth and is poised for further expansion in the coming years.
How much is the sodium-ion battery market worth in 2021?
The market for sodium-ion batteries was estimated to be worth roughly USD 1120 million in 2021, and it is anticipated to grow to USD 2899 million by 2030. The market is expected to grow significantly over the coming years as a result of a number of driving factors.
Why is the sodium-ion battery market growing?
Sodium-ion batteries play a crucial role in the transition towards cleaner and more abundant energy storage technologies and drive the Sodium-Ion Battery Market. The sodium-ion battery market demand is driven by the growing integration of renewable energy sources.
How will the sodium ion battery market grow in 2024?
The sodium ion battery market in the U.S. is expected to grow at a CAGR of 18.9% from 2024 to 2030. Increasing demand for sodium-ion batteries from sectors like electric utilities, transportation (potentially for low-range EVs or commercial fleets), and industrial applications requiring reliable and cost-effective energy storage.
How long does it take to download the sodium-ion battery report?
The sample report only takes 30 secs to download, no need to wait longer. The global sodium-ion battery market size was valued at USD 1025 million in 2021 and is estimated to reach an expected value of USD 2665 million by 2030, growing at a CAGR of 11.2% during the forecast period (2022 - 2030).
What are the types and end-users of the sodium-ion battery market?
The Sodium-ion Battery market is divided into types and end-users for the purposes of our study. The sodium-Sulfur batteries category is predicted to rule the sodium-ion battery market in 2021 based on type. In sodium-sulfur (NAS) batteries, a type of sodium-ion battery, there is a lithium sulphide cathode and a sodium anode.
-
Analysis of solar energy demand in Mexico
This Report provides an in-depth analysis of the Mexico solar energy market, including its meaning, executive summary, key market insights, market drivers, market restraints, market opportunities, .
FAQs about Analysis of solar energy demand in Mexico
What was the solar photovoltaic market like in Mexico in 2022?
In 2022, the solar photovoltaic (PV) market in Mexico recorded most of the deals in debt offerings, followed by asset transactions and partnerships. Mexico Solar PV Market Analysis by Deal Types, 2022 (%) Mexico Solar PV Market Deal Types Outlook (Cumulative Installed Capacity, MW, 2010-2035) This report provides:
Who are the market players in the solar power market in Mexico?
Energias Alternas SA de CV, Ecoturismo y Nuevas Tecnologias S.A. de C.V., Comision Federal de Electricidad, Alfa Solar, and Abengoa Mexico SA de CV are a few of the market players in the solar power market in Mexico. Energias Alternas SA de CV: The renewable energy company offers integrated solar photovoltaic systems and energy efficiency services.
Why is Mexico launching a solar financing wave?
In Mexico, the solar financing wave is being fueled in large part by the country's renewable energy goals, which are 35% by 2024 and 50% by 2050. The higher investment and government policies are expected to provide good opportunity to the Mexican solar energy market during the forecast period.
What is the solar PV market size in Mexico?
The cumulative installed capacity for solar PV in Mexico was 9,338.7MW in 2022 and will achieve a CAGR of more than 10% during 2022-2035. The Mexico Solar Photovoltaic (PV) market research report offers comprehensive information and understanding of the solar PV market in Mexico.
What are the key highlights of the Mexican solar PV market?
The Mexican renewable power market is led by the solar PV market with a cumulative installed capacity of 9,338.7MW by the end of 2022. This will increase at a CAGR of more than 10% during 2022-2035. The following are some of the key highlights of the Mexico Solar PV market:
Are solar panels becoming a trend in Mexico?
However, gradually, residential and commercial buildings in the urban areas also began installing solar PV panels. Though distributed solar generation is still in a nascent stage in Mexico, it witnessed a rapid growth in the last few years.
-
Lead-acid battery market trend analysis
The lead-acid battery market features established players like EnerSys, Clarios, GS Yuasa, Exide Industries, and Amara Raja Batteries leading the industry through continuous innovation and strategic expansion. These lead-acid battery companies are focusing on developing advanced lead-acid battery technologies,. The lead-acid battery market demonstrates a balanced mix of global conglomerates and regional specialists, with established. Success in the lead-acid battery market increasingly depends on companies' ability to innovate while maintaining cost competitiveness and meeting environmental standards.
FAQs about Lead-acid battery market trend analysis
What is the global lead acid battery market size?
The global lead acid battery market size was valued at USD 37.98 billion in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 4.6% from 2023 to 2030.
Why is the lead acid battery market growing?
The market is estimated to witness growth owing to the growing adoption of lead acid batteries in automobiles and Uninterruptible Power Source (UPS) along with some developments in the manufacturing methods. The increasing demand for lead acid batteries in off-grid power generation is expected to boost the market size.
What is the growth rate of lead acid batteries industry in 2022?
The growing demand in various industries including the medical industry, educational institutes, corporate offices, research institutions, and houses promises further growth during the forecast period. Asia Pacific dominated the lead acid batteries industry and accounted for more than 55.0% share of the global revenue in 2022.
Which region dominated the lead acid battery industry in 2023?
Asia Pacific dominated the lead acid battery industry with a market share of 39.26% in 2023. Lead acid battery, also known as a lead storage battery, is a rechargeable battery that uses lead and sulfuric acid materials for function. Although lead acid batteries are highly reliable, they have minimal life.
What are the key characteristics of the lead acid battery market?
Mergers & acquisitions and joint ventures are key characteristics of the market players, to increase their market presence. The industry is highly competitive with participants involved in continuous product innovation and R&D. Some prominent players in the global lead acid battery market include:
Who makes lead acid batteries?
Key lead-acid battery manufacturers, including Crown Battery, EnerSys, C&D Technologies, East Penn Manufacturing, and NorthStar, largely drive the growth of the North American lead acid battery market share. These companies are focused on product development, which leads to the introduction of advanced lead-acid batteries in the market.