Related Topics:
Supercapacitor Technology Market Growth-
Photovoltaic glass profit in 2025
The Asia-Pacific region dominates the global solar photovoltaic glass market with significant manufacturing capabilities and installations across major economies. China leads the manufacturing landscape, while.
FAQs about Photovoltaic glass profit in 2025
What is the global photovoltaic glass market size?
Region : Global | Format: PDF | Report ID: BRI102553 | SKU ID: 21776130 The global photovoltaic glass market size was USD 6.5 billion in 2024 & the market is expected to reach USD 26.4 billion by 2033, exhibiting a CAGR of 16.85% during the forecast period.
Will Photovoltaic Glass market grow in North America?
The photovoltaic glass market in North America is anticipated to grow at a highestCAGR in terms of value-energy utilization over the forecast period, whereas the market is anticipatedto represent an important incremental possibility over the coming years. "Key Players Focus on Partnerships to Gain a Competitive Advantage "
Who are the major players in the Solar Photovoltaic Glass market?
The solar photovoltaic glass market is consolidated in nature. The major players in this market include Xinyi Solar Holdings Limited, Flat Glass Group Co., Ltd, AGC Inc., Nippon Sheet Glass Co., Ltd, and Saint-Gobain, among others (not in a particular order). Need More Details on Market Players and Competitors?
What are the main trends in the photovoltaic market?
Rising research and developmentsefforts and green building market dynamics are the main trends seen in the photovoltaic market.
Which region will dominate the Solar Photovoltaic Glass market?
The Asia-Pacific region is expected to dominate the solar photovoltaic glass market. In developing countries like China, India, and Japan, the crisis in electricity supply has resulted in increasing the scope for self-producing electricity using solar photovoltaic glass.
Can Photovoltaic Glass reduce energy costs?
In addition to lowering energy costs, photovoltaic glass use has the potential to improve marketing and public relations by lowering facilities' thus promotingcarbon footprints and promoting sustainability.
-
What will be the cost of one watt of energy storage in 2025
In 2025, the cost per kWh is between $200 and $400. The price changes based on the technology and where you live. Lithium-ion batteries, like LFP and NMC, are the most common.
FAQs about What will be the cost of one watt of energy storage in 2025
How much does a battery cost in 2025?
In 2025, you're looking at an average cost of about $152 per kilowatt-hour (kWh) for lithium-ion battery packs, which represents a 7% increase since 2021. Energy storage systems (ESS) for four-hour durations exceed $300/kWh, marking the first price hike since 2017, largely driven by escalating raw material costs and supply chain disruptions.
How much does energy storage cost in 2024?
As we look ahead to 2024, energy storage system (ESS) costs are expected to undergo significant changes. Currently, the average cost remains above $300/kWh for four-hour duration systems, primarily due to rising raw material prices since 2017.
Will battery storage prices continue to decline in 2025?
We expect to see battery storage prices continue to decline in 2025, even as raw material prices rise, due to the oversupply of battery production. The rapid growth of battery manufacturing, particularly in China and Europe, has outpaced demand, which is exerting downward pressure on pricing.
How much does energy storage cost?
Energy storage system costs for four-hour duration systems exceed $300/kWh for the first time since 2017. Rising raw material prices, particularly for lithium and nickel, contribute to increased energy storage costs. Fixed operation and maintenance costs for battery systems are estimated at 2.5% of capital costs.
Why are energy storage systems so expensive?
Energy storage systems (ESS) for four-hour durations exceed $300/kWh, marking the first price hike since 2017, largely driven by escalating raw material costs and supply chain disruptions. Geopolitical issues have intensified these trends, especially concerning lithium and nickel.
Why are lithium-ion batteries so expensive in 2025?
In 2025, lithium-ion battery pack prices averaged $152/kWh, reflecting ongoing challenges, including rising raw material costs and geopolitical tensions, particularly due to Russia's war in Ukraine. These factors have led to high prices for essential metals like lithium and nickel, impacting the production of energy storage technologies.
-
Abu Dhabi 2025 Solar Photovoltaic Panel Project
Masdar and Emirates Water and Electricity Co. (EWEC) plan to build a $6 billion, 5 GW/19 GWh solar-plus-storage project in Abu Dhabi, with operations set to start by 2027.
FAQs about Abu Dhabi 2025 Solar Photovoltaic Panel Project
How many solar panels will Abu Dhabi have by 2035?
By 2035, EWEC forecasts at least 18GW of solar PV in operation, supporting the Abu Dhabi Department of Energy's Clean Energy Strategic Target 2035, aiming to meet 60 percent of the emirate's power demand through renewable and clean energy sources.
Will Abu Dhabi be home to a 5.2-gw solar farm?
Abu Dhabi will soon be home to a 5.2-GW solar farm – snagging the top spot on the global solar energy plant leaderboard. That's part of a gigascale project set to be built in the capital of the United Arab Emirates by Abu Dhabi Future Energy Company aka Masdar, and Emirates Water and Electricity Company.
Will Abu Dhabi be the world's first '24/7' solar farm?
Abu Dhabi will soon be home to a 5.2-GW solar farm – snagging the top spot on the global solar energy plant leaderboard. It'll be the world's first '24/7' solar photovolatic plant coupled with a Battery Energy Storage System (BESS).
Will Masdar & EWEC build a solar-plus-storage project in Abu Dhabi?
Masdar and Emirates Water and Electricity Co. (EWEC) plan to build a $6 billion, 5 GW/19 GWh solar-plus-storage project in Abu Dhabi, with operations set to start by 2027. Emirati state-owned renewable investment company Masdar is partnering with EWEC to build a giant solar and battery energy storage (BESS) facility.
Why should UAE invest in solar power & battery energy storage?
The world-leading project reflects the vision and commitment of the UAE leadership in driving socioeconomic and environmental progress. The accelerated integration of solar power and advanced battery energy storage sets a new benchmark in clean energy, driving sustainability and reducing carbon emissions.
Who is building the world's largest solar and battery storage project?
The United Arab Emirates is building the world's largest solar and battery storage project that will dispatch clean energy 24/7. Emirati Renewable energy company Masdar (Abu Dhabi Future Energy Company) and Emirates Water and Electricity Company (EWEC) are developing the trailblazing solar and battery storage project.
-
Huawei Energy Storage Inverter 2025
At Intersolar Europe 2025, Huawei Digital Power's Intelligent PV Business Unit today launched a groundbreaking full-scenario grid-forming energy storage platform and a next-gen residential energy management system, setting new benchmarks for safety, scalability, and smart grid integration in the renewable energy sector.
FAQs about Huawei Energy Storage Inverter 2025
What is a Huawei inverter?
Huawei inverters are becoming a benchmark for solar energy in residential and commercial applications. Huawei is a well-known brand in the solar energy sector.
What happened at Huawei fusionsolar 2025?
On April 8, 2025, Huawei hosted a FusionSolar Industrial and Commercial Flagship Summit in Frankfurt, Germany. The theme was Future Energy Goals. Tong Jinly, the President of Huawei Digital Energy Global Industrial and Commercial Sales and Services, unveiled a new smart Hybrid cooling energy storage solution in Europe.
What is Huawei fusionsolar & SNEC PV+ 2025?
Huawei FusionSolar will showcase its latest smart PV and energy storage products, along with the upgraded all-scenario grid-forming solutions at SNEC PV+ 2025. The event will be held in Hall 6.1 at the National Exhibition and Convention Center in Shanghai from June 11 to 13, 2025.
Can the inverter be extended with the Huawei battery?
Thanks to the integrated 800V high-voltage battery connection, the inverter can be extended with the HUAWEI Battery. The optional HUAWEI Smart Meter is connected via the integrated RS485 interface and provides information about house consumption and grid feed-in.
What's new at Intersolar Europe 2025?
At Intersolar Europe 2025, Huawei Digital Power's Intelligent PV Business Unit today launched a groundbreaking full-scenario grid-forming energy storage platform and a next-gen residential energy management system, setting new benchmarks for safety, scalability, and smart grid integration in the renewable energy sector.
What's new at Huawei in 2025?
Join Huawei from June 11 to 13, 2025, in Hall 6.1 at the National Exhibition and Convention Center in Shanghai, China, as we unveil our next-generation PV+ESS products and cutting-edge all-scenario grid-forming solutions.
-
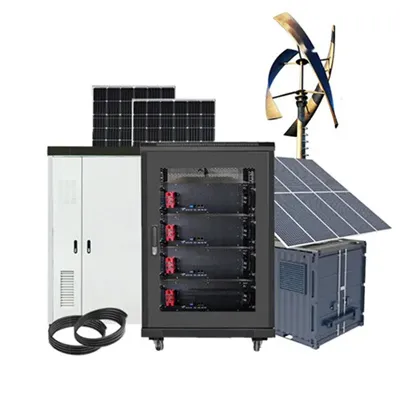
2025 Base station backup energy storage demand
Global energy storage installations are projected to grow by 76% in 2025 according to BloombergNEF, reaching 69 GW/169 GWh as grid resilience needs and demand balloon.
FAQs about 2025 Base station backup energy storage demand
How big will energy storage be in 2025?
Global energy storage installations are projected to grow by 76% in 2025 according to BloombergNEF, reaching 69 GW/169 GWh as grid resilience needs and demand balloon. Global energy storage projections are staggering, with a potential acceleration to 1,500 GW by 2030 following the COP29 Global Energy Storage and Grids Pledge.
What is the future of energy storage?
Global installed energy storage is on a steep upward trajectory. From just under 0.5 terawatts (TW) in 2024, total capacity is expected to rise ninefold to over 4 TW by 2040, driven by battery energy storage systems (BESS). Last year saw a record-breaking 200 gigawatt-hours (GWh) of new BESS projects coming online, a growth rate of 80%.
Will battery storage grow in 2025?
In the United States, the 2022 introduction of the Inflation Reduction Act included an investment tax credit for stand-alone storage. Since then we have seen huge growth in the sector in the US, and we expect to see this to continue into 2025, with several large-scale battery storage projects set to complete in 2025.
Will energy storage grow in 2024?
The energy storage sector maintained its upward trajectory in 2024, with estimates indicating that global energy storage installations rose by more than 75%, measured by megawatt-hours (MWh), year-over-year in 2024 and are expected to go beyond the terawatt-hour mark before 2030.
Will energy storage development continue to grow in the United States?
Amid ongoing conversations about grid reliability amid growing electricity demand driven in part by booming expansion of data centers and continuing interest in moving away from fossil fuels toward intermittent renewable resources, energy storage development will continue to grow across the United States.
How many energy storage financing and investment deals were completed in 2024?
Through the first three quarters of 2024, 83 energy storage financing and investment deals were reported completed for a total of $17.6 billion invested. Of these transactions, 18 were M&A transactions, up from 11 transactions during the same period in 2023.
-
Burkina Faso Energy Storage 2025
The Government of Burkina Faso has signed a Public-Private Partnership (PPP) agreement with a local developer and a Dutch clean energy investment firm to develop a major solar and battery storage system.
-
Lithium Battery Energy Storage Trends 2025
While lithium-ion batteries have traditionally served short-duration needs, recent projects are pushing beyond conventional 4-6 hour limits, with 8-10 hour lithium-ion systems now appearing in grid-scale applications, challenging established assumptions about technology constraints.
FAQs about Lithium Battery Energy Storage Trends 2025
What are the market trends of lithium-ion batteries?
Market trends of lithium-ion batteries The market trends of lithium-ion batteries are dynamic and reflective of the evolving landscape of energy storage technologies. Lithium-ion batteries have experienced substantial growth, driven by their widespread adoption in diverse applications.
Are lithium-ion batteries the future of energy storage?
While lithium-ion batteries have dominated the energy storage landscape, there is a growing interest in exploring alternative battery technologies that offer improved performance, safety, and sustainability .
What is the future of lithium ion batteries?
Recent advancements enable 80 % recharge in under 30 min, enhancing usability in transportation and consumer applications. The demand for lithium-ion batteries is rapidly expanding, particularly in EVs and grid energy storage. Improved recycling processes and alternative materials are critical for minimizing environmental impact.
Will lithium-ion battery demand increase in 2025?
In 2020, global sales of EVs reached 1.5 million units, with a corresponding lithium-ion battery demand of 65 GWh. Projections indicate a substantial increase to 137 GWh in 2025 and 245 GWh in 2030, emphasizing the pivotal role of lithium-ion batteries in the automotive industry.
Can technology improve sustainability in lithium-ion batteries?
Recent research by Li et al. explores technological innovations in lithium-ion battery design to improve sustainability. The study focuses on developing cathodes with reduced reliance on critical materials like cobalt, aiming to enhance the environmental profile of batteries.
How long do lithium-ion batteries last?
While lithium-ion batteries have traditionally served short-duration needs, recent projects are pushing beyond conventional 4-6 hour limits, with 8-10 hour lithium-ion systems now appearing in grid-scale applications, challenging established assumptions about technology constraints.
-
China develops battery technology research
China plans to invest more than 6 billion yuan ($830 million) in a government-led project to develop solid-state batteries with six firms eligible for state funding to work on the next-generation t.
FAQs about China develops battery technology research
Why is China leading the world in battery research?
Researchers in China lead the world in publishing widely cited papers in 52 of 64 critical technologies, recent calculations by the Australian Strategic Policy Institute reveal. China's advances in battery research have helped it gain a dominant position in electric vehicles. Gilles Sabrié for The New York Times
Which advanced battery materials are made in China?
In this perspective, we present an overview of the research and development of advanced battery materials made in China, covering Li-ion batteries, Na-ion batteries, solid-state batteries and some promising types of Li-S, Li-O 2, Li-CO 2 batteries, all of which have been achieved remarkable progress.
What will China's battery industry be like until 2030?
Xu Yanhua, secretary of the China Automotive Battery Innovation Alliance, said that until 2030, the country's power battery industry will still be dominated by high-energy-density liquid batteries and lithium iron phosphate batteries.
Where does China's lead in battery technology come from?
China's lead is particularly wide in batteries. According to the Australian Strategic Policy Institute, 65.5 percent of widely cited technical papers on battery technology come from researchers in China, compared with 12 percent from the United States. A CATL battery factory in Ningde, China, last year. Qilai Shen for The New York Times
Is China outpacing other countries in battery chemistry?
Stressing science education, China is outpacing other countries in research fields like battery chemistry, crucial to its lead in electric vehicles. CATL, a leading battery maker, showcased its technology at a Shanghai auto trade show last year. Qilai Shen for The New York Times
Why are Chinese companies pursuing alternative batteries not based on lithium?
Lithium technologies are expected to advance quickly over the next few years. However, companies in China and beyond are frantically pursuing alternative batteries not centred around lithium, in part because the minerals needed to make the current options come from just a few countries.
-
Peak shaving energy storage technology
Peak shaving, or load shedding, is a strategy for eliminating demand spikes by reducing electricity consumption through battery energy storage systems or other means.
FAQs about Peak shaving energy storage technology
What are the advantages of peak shaving in thermal power units?
At the same time, it also has the advantages of high energy storage density, long energy storage cycle, and low cost, making it one of the very promising peak shaving methods for thermal power units.
Should energy storage system be used for peak shaving?
An energy storage system (ESS) application is more advantageous than the demand response program, where it allows customers to simultaneously shave peak load and perform daily activities as usual. Therefore, future research should emphasise on the proper application of DSM with ESS system for peak shaving purpose.
What are peak load shaving strategies?
In this study, a significant literature review on peak load shaving strategies has been presented. The impact of three major strategies for peak load shaving, namely demand side management (DSM), integration of energy storage system (ESS), and integration of electric vehicle (EV) to the grid has been discussed in detail.
What is deep peak shaving?
Author to whom correspondence should be addressed. Deep peak shaving achieved through the integration of energy storage and thermal power units is a primary approach to enhance the peak shaving capability of a system.
Which energy storage technology is used for peak load shaving?
Among various energy storage technologies, electrochemical technology based BESS is mostly used for peak load shaving. The use of different battery energy storage technologies for peak shaving can be found in the previous literature, , , , , , , .
Does peak shaving help reduce energy costs?
Peak shaving can help reduce energy costs in cases where peak loads coincide with electricity price peaks. This paper addresses the challenge of utilizing a finite energy storage reserve for peak shaving in an optimal way.
-
Brief introduction to the application of energy storage technology
The development of thermal, mechanical, and chemical energy storage technologies addresses challenges created by significant penetration of variable renewable energy sources into the electricity mix. Ren. Energy storage systems help to bridge the gap between power generation and demand. Energy storage employs and exploits the true fundamentals of Thermodynamics. As such, it is appropriate to begin the discussion with first principles. This section will provide an ov. The many forms of energy have resulted in a wide range of technologies that seek to store and convert energy, some of which are commercially mature and others that are currently und. 1.“BP Statistical Review of World Energy,” 68th ed., 2019.Google Scholar2.“Electricity Information: Overview,” International Ene.
FAQs about Brief introduction to the application of energy storage technology
What is energy storage technology?
The development of thermal, mechanical, and chemical energy storage technologies addresses challenges created by significant penetration of variable renewable energy sources into the electricity mix.
Why are energy storage technologies undergoing advancement?
Energy storage technologies are undergoing advancement due to significant investments in R&D and commercial applications. For example, work performed for Pacific Northwest National Laboratory provides cost and performance characteristics for several different battery energy storage (BES) technologies (Mongird et al. 2019). Figure 26.
What are the applications of energy storage system (ESS)?
The ESS could be also used in case of a general blackout for the re-starting of the entire electrical system. As mentioned above, there are many applications for energy storage systems and several benefits for the electrical system where an energy storage system is present.
How can research and development support energy storage technologies?
Research and development funding can also lead to advanced and cost-effective energy storage technologies. They must ensure that storage technologies operate efficiently, retaining and releasing energy as efficiently as possible while minimizing losses.
When was energy storage first used?
The earliest grid-scale energy storage technology is pumped hydroelectric storage, introduced to the grid in the 1930s. Significant capacity growth has continued since, and pumped hydro is still the dominant technology in energy storage on a capacity basis.
Are energy storage systems a key enabling technology for renewable power generation?
Energy storage systems that can operate over minute by minute, hourly, weekly, and even seasonal timescales have the capability to fully combat renewable resource variability and are a key enabling technology for deep penetration of renewable power generation.
-
Analysis of Tantalum Capacitor Market Situation
The study offers a detailed analysis of global consumption value, volume and ASPs for tantalum capacitors by type, configuration, size, region and end-use market segment with detailed for forecasts.
FAQs about Analysis of Tantalum Capacitor Market Situation
What is a tantalum capacitor used for?
Its main use today is in tantalum capacitors in electronic devices such as cell phones, DVD players, video game systems, and computers. The tantalum market is segmented by product, application, and geography. The market is segmented by products, such as metal, carbide, powder, alloys, and other product forms.
Should we replace solid capacitors with polymer tantalum capacitors?
Replacing solid capacitors with polymer tantalum capacitors is expected to act as an opportunity for the studied market. On the flip side, the harmful effects of tantalum and the decrease in demand from end-user industries are hindering the market's growth.
How is the tantalum market segmented?
The tantalum market is segmented by product, application, and geography. The market is segmented by products, such as metal, carbide, powder, alloys, and other product forms. The market is segmented by application into capacitors, semiconductors, engine turbine blades, chemical processing equipment, medical equipment, and other applications.
How reliable are tantalum capacitors?
Modern tantalum capacitors are very reliable if used properly. That includes having a series resistance of at least 0.1 to 3 ohms in the circuit, derating the voltage to about 60% maximum of the rated voltage and keeping the temperature to a reasonable value. They must never, even briefly, be exposed to any reverse voltage.
Which countries use tantalum electrolytic capacitors?
Asia-Pacific dominates the market across the world, with the largest consumption from countries such as China and South Korea. A tantalum electrolytic capacitor is made of tantalum (Ta) metal as anode material, which can be divided into foil and tantalum powder sintered types according to different anode structures.
Why do tantalum capacitors fail?
Tantalum capacitors may fail relatively quickly with added ripple voltage. High relative humidity and high temperature both affect water diffusion, but increased ripple voltage in 85/85 testing causes tantalum capacitor characteristics to weaken and capacitors to fail. (1. Introduction)
-
How to analyze the current market of lead-acid batteries
In this article, we'll explore the current state of the lead-acid battery industry, its technological progress, and the key trends that will shape its role in the years to come.
FAQs about How to analyze the current market of lead-acid batteries
What is the global lead acid battery market size?
The global lead acid battery market size was valued at USD 45.84 billion in 2023 and is projected to grow from USD 48.32 billion in 2024 to USD 71.68 billion by 2032, exhibiting a CAGR of 5.05% during the forecast period. Asia Pacific dominated the lead acid battery industry with a market share of 39.26% in 2023.
What is a lead acid battery?
Lead acid battery, also known as a lead storage battery, is a rechargeable battery that uses lead and sulfuric acid materials for function. Although lead acid batteries are highly reliable, they have minimal life. The battery also contains some toxic materials, which require unique removal methods at the end of their life.
Which region dominated the lead acid battery industry in 2023?
Asia Pacific dominated the lead acid battery industry with a market share of 39.26% in 2023. Lead acid battery, also known as a lead storage battery, is a rechargeable battery that uses lead and sulfuric acid materials for function. Although lead acid batteries are highly reliable, they have minimal life.
Who makes lead acid batteries?
Key lead-acid battery manufacturers, including Crown Battery, EnerSys, C&D Technologies, East Penn Manufacturing, and NorthStar, largely drive the growth of the North American lead acid battery market share. These companies are focused on product development, which leads to the introduction of advanced lead-acid batteries in the market.
How big is the lead-acid battery market?
Lead-Acid Battery Market Research, 2032 The global lead-acid battery market was valued at $52.1 billion in 2022, and is projected to reach $81.4 billion by 2032, growing at a CAGR of 4.6% from 2023 to 2032.
What are the major players in the lead acid battery market?
Competitive Analysis The major players operating in the lead acid battery market include EnerSys, Crown Battery, East Penn Manufacturing Company, Inc., HOPPECKE, NorthStar, Hitachi Ltd., Exide Technologies, LLC, Teledyne Technologies Incorporated, Hankook AltasBX, and C&D Technologies. .
-
What technology is used to process n-type batteries
N-Type technology refers to the use of phosphorus-doped silicon as the base material for solar cells, which inherently has a negative (n) charge due to the extra electrons provided by phosphorus.
FAQs about What technology is used to process n-type batteries
Can n-type organic materials be used in a battery system?
While many reviews have evaluated the properties of organic materials at the material or electrode level, herein, the properties of n-type organic materials are assessed in a complex system, such as a full battery, to evaluate the feasibility and performance of these materials in commercial-scale battery systems.
Can n-type materials be used in commercial-scale battery systems?
The n-type materials have the potential to offer an economical and sustainable solution for energy storage applications. 17, 20, 36 However, further insights are needed to evaluate the feasibility and performance of these materials in commercial-scale battery systems.
Why do p-type materials behave differently than typical lithium-ion battery electrodes?
The p-type materials also behave differently from typical lithium-ion battery electrodes due to the fundamental role of the electrolyte as a source of anions in the redox reaction, hence they are similar to lead-acid battery electrodes. 33 - 35
What are the different types of n-type cell technology?
N-type cell technology can be subdivided into heterojunction (HJT), TOPCon, IBC and other technology types. Currently, PV cell manufacturers mostly choose TOPCon or HJT to pursue mass production. The theoretical efficiency of N-type TOPCon cells can reach 28.7%, and the theoretical efficiency of heterojunction cells can reach 27.5%.
Can a physical processing route be used to recycle Li-ion battery cells?
The aim of this work was to propose an integrated physical processing route for recycling different Li-ion battery cells (pouch, cylindrical, and prismatic) and cathodes (NMC and NMC-LMO) for hydrometallurgical treatment in a single route.
Are organic batteries a viable alternative to traditional lithium-ion batteries?
Traditional lithium-ion batteries, while instrumental in this energy transition, face challenges including resource scarcity and environmental concerns due to their metal components. Organic electrode materials have emerged as promising alternatives, offering advantages such as sustainability, cost-efficiency, and design flexibility.